Pakistan’s Auto Policy 2026–31 Draft Proposes EV Incentives and Export Support
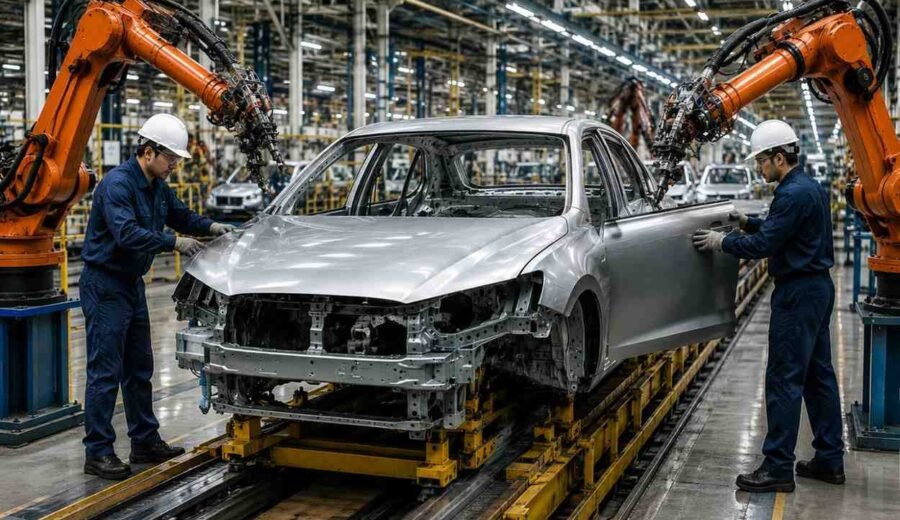
Pakistan’s proposed Auto Policy 2026–31 aims to promote competition, accelerate new energy vehicle (NEV) adoption and strengthen the country’s automotive export potential. The Ministry of Industries and Production released the updated draft on October 20, 2026.
However, the draft is still subject to approval from the International Monetary Fund (IMF) and the Government of Pakistan. The approval process is expected to take a few weeks, after which the policy may be formalised through a supplementary Finance Bill passed by Parliament.
Revised GST Rates to Favour Battery Electric Vehicles
The updated draft retains a 1% General Sales Tax (GST) rate for battery electric vehicles (BEVs), while proposing a 9% rate for plug-in hybrid electric vehicles (PHEVs) and 6% for range-extended electric vehicles (REEVs).
This marks a change from the September 8 draft, which proposed a uniform 1% GST rate across all NEV categories. Under the previous policy, PHEVs faced GST rates ranging from 8.5% to 12.75%.
The proposed structure continues to favour fully electric vehicles, potentially creating opportunities for companies with established NEV portfolios or plans to enter the market.
Among listed companies, analysts identify Sazgar Engineering Works Limited (SAZEW), Nishat Group companies Nishat Chunian Power Limited (NCPL) and Nishat Power Limited (NPL), and Hub Power Company (HUBC), through its BYD-related business, as potential beneficiaries of the growing NEV market.
Auto Financing Limit Proposed to Rise to Rs10 Million
The draft retains the proposal to increase the maximum auto financing limit from Rs3 million to Rs10 million. It also proposes extending the maximum financing tenure from three years to five years.
If approved, these changes could improve vehicle affordability by allowing buyers to finance more expensive vehicles over longer repayment periods. The measures may support demand and expand access to vehicle financing across the country.
Export Incentives Target Higher Automotive Shipments
The revised draft proposes a Drawback of Local Taxes and Levies (DLTL) incentive comprising baseline support of 5% of net free-on-board (FOB) export value, alongside an additional 10% incentive on incremental exports, subject to minimum year-on-year growth of 5%.
The proposed incentive could encourage automotive manufacturers to expand export volumes, improve competitiveness and develop Pakistan as a stronger regional production base. Its effectiveness will depend on the final eligibility conditions, implementation mechanism and manufacturers’ ability to achieve the required export growth.
Lower CKD Tariffs May Pressure Local Vendors
The draft proposes reducing tariffs on localised completely knocked-down (CKD) automotive parts to 15% by FY31, compared with the 25% rate proposed in the earlier draft.
Lower tariffs could reduce input costs for vehicle assemblers and support improvements in gross margins. However, the change may also increase pressure on domestic auto-parts manufacturers by reducing the tariff protection available to local suppliers.
Intensifying competition could encourage assemblers to pass some of the cost savings on to consumers through more competitive vehicle prices.
Automotive Development Levy Revised
The proposed Automotive Development Levy would vary according to engine capacity. The latest draft sets the levy at 0% for internal combustion engine (ICE) vehicles below 1,000cc, 2% for vehicles between 1,000cc and 2,000cc, and 10% for vehicles above 2,000cc.
These rates replace the earlier draft’s proposed levy of 4.5% to 5.5% across engine categories.
The revised structure would place a greater levy burden on vehicles with larger engines, while exempting vehicles below 1,000cc. The impact on vehicles below 2,000cc, including the Toyota Corolla and Honda City, is expected to be relatively limited under the proposed rates. Any offset from lower CKD tariffs would depend on the final policy structure and how manufacturers respond.
Policy Approval Remains the Key Milestone
The proposed Auto Policy 2026–31 combines incentives for electric vehicle adoption and automotive exports with changes to financing and tariff structures. While the measures could create opportunities for vehicle assemblers and NEV-focused businesses, the proposed reduction in CKD tariffs may pose challenges for the local vendor industry.
The draft is not yet final. Its impact on manufacturers, consumers and investors will depend on IMF and government approval, the final policy provisions and the implementation timeline.
RELATED STORIES